Life Insurance With Long-Term Flexibility
Indexed Universal Life (IUL) is permanent life insurance combining a death benefit with cash value whose credited interest may be linked in part to the performance of a market index.
What Is Indexed Universal Life Insurance?
Indexed Universal Life (IUL) is permanent life insurance combining a death benefit with cash value whose credited interest may be linked in part to the performance of a market index. The policy is not directly invested in the stock market or market index.
Interest credited to the policy’s cash value may be influenced by the performance of an external index, subject to policy provisions including caps, participation rates, spreads, and floors. Insurance costs and policy charges also affect the policy’s value.
Protection + Cash-Value Potential
An IUL may be considered for several potential objectives:
Permanent Insurance
Coverage designed to last a lifetime, subject to policy terms.
Cash-Value Accumulation
Potential for cash-value growth linked in part to an index.
Flexible Policy Features
Ability to adjust premiums and death benefit, subject to policy terms.
Supplemental Resources
Potential access to cash value through loans or withdrawals.
Legacy Planning
Support for creating and leaving a meaningful legacy.
IUL Is a Long-Term Strategy
Schedule an IUL Consultation
Schedule a Free ConsultationWhat Happens When the Market Falls?
Index-Crediting Floor
Many IUL policies include a 0% index-crediting floor, meaning the index-crediting rate may not fall below zero based on index performance alone.
Cash Value Can Still Decline
A 0% index-crediting floor does not mean the policy’s cash value cannot decline. Policy charges, insurance costs, loans, withdrawals, and other factors can reduce policy value.
Not a Stock Market Investment
The policy is not directly invested in the stock market or market index. Interest crediting is subject to caps, participation rates, spreads, and contract provisions.
Long-Term Commitment
IUL is a long-term strategy. Policy design and funding matter significantly, and early surrender may result in charges or loss of value.
Guidance From Someone Who Understands Families
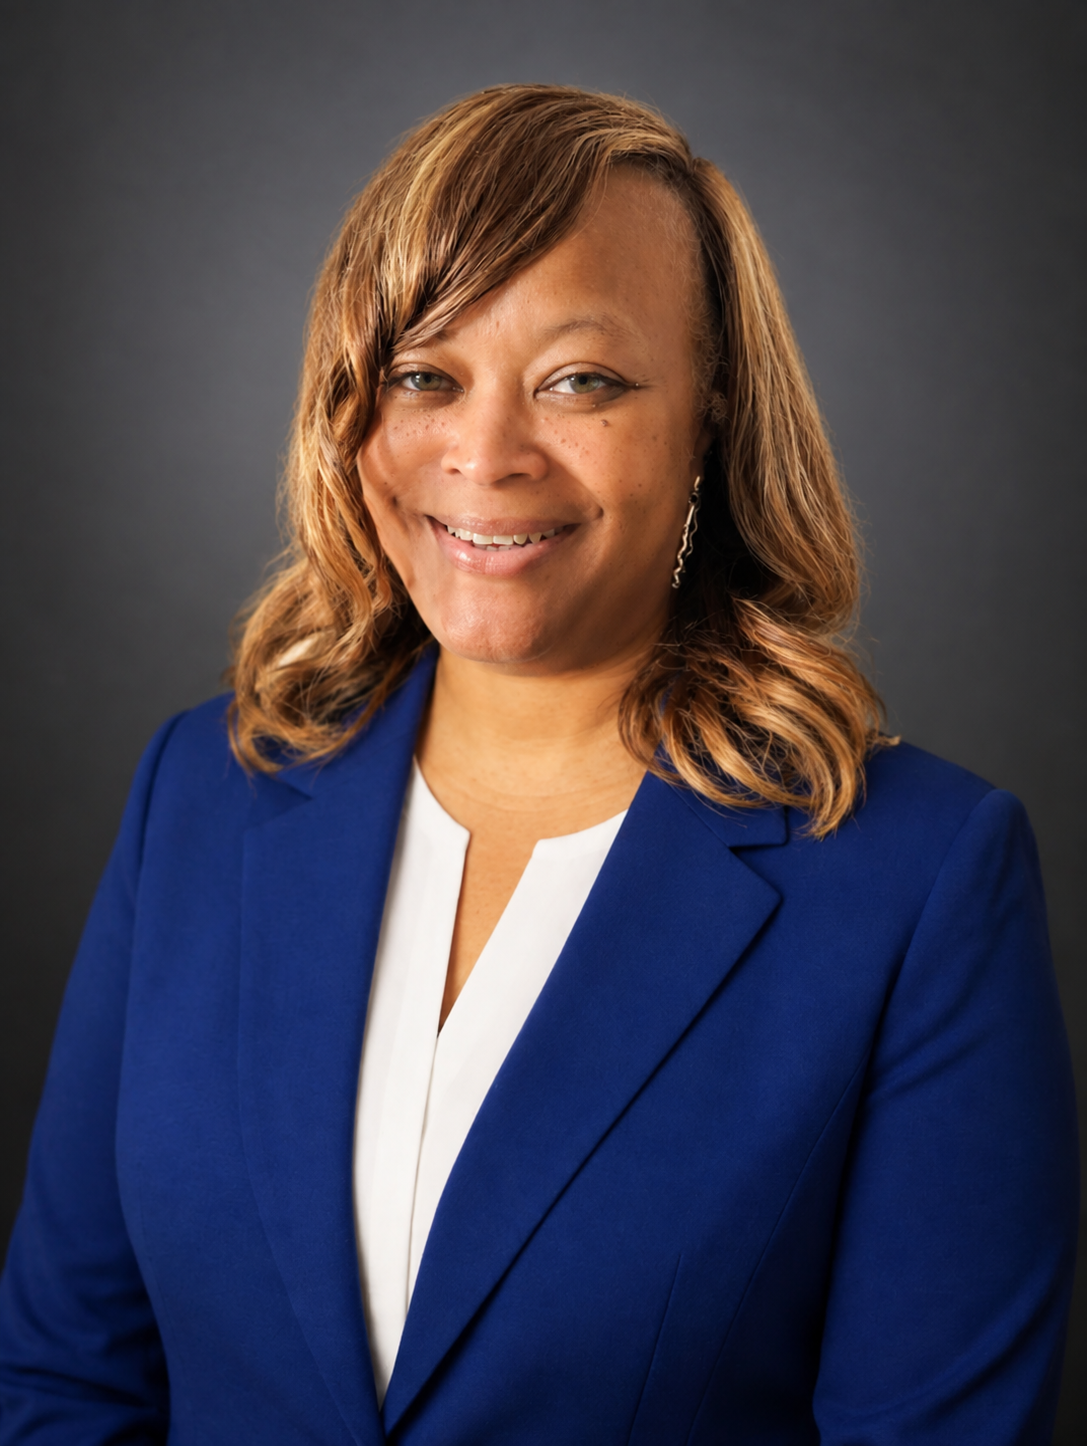
Work directly with Keona DuBose.
I’m the founder of Life Legacy Collective, and my story starts long before I became a life insurance agent. For more than 25 years, I worked in social services and case management, walking alongside individuals and families during some of the most difficult seasons of their lives. I helped people navigate crisis, find resources, and move forward with hope. Through that work — and through my own personal experiences — I saw one truth over and over again:
Frequently Asked Questions
Not Sure Which Solution Is Right for You?
You don’t have to figure it out alone.
Life insurance and retirement solutions can vary significantly based on your age, family responsibilities, financial goals, health, budget and long-term objectives.
Work directly with Keona DuBose to discuss your goals, understand your options and explore solutions that may be appropriate for your situation.
KEONA DUBOSE
Licensed Life Insurance Agent
Life Legacy Collective
No obligation. Your consultation is an opportunity to ask questions and better understand your available options.
Indexed Universal Life (IUL) is permanent life insurance. The policy is not directly invested in the stock market or market index. Interest crediting is subject to policy provisions including caps, participation rates, spreads, and floors. Policy charges, insurance costs, loans, and withdrawals can reduce policy value. This page is for educational purposes and is not an offer of coverage.